
What a first screen is for
Most of what reaches you should not even get past the first ten minutes of the screen. This first screen decides whether a case gets real work, and nothing else. It sits at a fixed point right at the beginning of your decision process.
- Incoming case
- Prescreening
- Screening and analysis
- Term sheet
- Due diligence (selskapsgjennomgang)
- Shareholders’ agreement and investment agreement
- Signing
- Kick-off and the 100-day plan
Everything before the term sheet is triage, and the screen is the cheapest gate that you run alone without asking the founder for anything.
A low single-digit share of applicants ends in an investment. The numbers say declining an investment is the normal outcome, so build a routine that expects to decline most companies you review. In the standard group funnel described by the Angel Capital Association, about 10 to 25 percent of applicants reach the screening or presentation stage, but 25 to 50 percent of the companies that get as far as due diligence end up being funded.
Also remember to first and foremost screen the business and ignore the quality of the paperwork. When reviewing the most important thing is to score according to the criteria and ignore how well the applicant has completed the form, because a bad application can be a fantastic case, and founders who write badly are common. The same can be seen in pitch competitions, where you hear amazing pitches for companies that never get off the ground, and stuttering pitches for what could end up becoming world changing cases.
Hard blockers: what ends the screen immediately
Check these first, because any one of them ends the screen and saves you the rest of the twenty minutes. Which of them you apply is your decision.
| Blocker | What it looks like, and why later work cannot fix it |
|---|---|
| Unwilling to work with angels | Wants money without governance, reporting or advice, and treats questions as intrusion. Angel capital comes with angel involvement, that is not negotiable. |
| Unwilling to share and dilute | Refuses to go below a fixed ownership share, or talks about “giving away” equity. The round cannot be priced, and neither can any future round. |
| Unwilling to accept lock-up | Wants freedom to sell or exit ahead of the other shareholders. Lock-up is the commitment the rest of the cap table is buying. |
| Valuation expectation out of range | A price that only clears if everything goes right and nothing costs anything. Diligence cannot argue a founder down from a number that is identity rather than analysis. |
| Team | A single founder with no plan to fill the gaps, or a team that cannot describe its own division of labor. At this stage you are underwriting execution and nothing else. |
| Case | No defensible activity, or an idea that is a feature of someone else’s product. The problem is the business itself, however it is presented. |
| Governance | A broken cap table, dormant shareholders holding large blocks, or unresolved past disputes. Every future round has to renegotiate the past before it can price the future. |
| Title and patent | The company does not own its core technology, code or brand. Ownership defects are slow and expensive to repair, and some cannot be. |
| Diligence access | Unwilling to open books, contracts or the register to scrutiny. A no now will be a no when your money is at risk. |
| Finance | No control of cash, no budget, or a funding need the round on offer cannot reach. An underfunded round gives you a shorter runway and the same problem again. |
A blocker ends the screen, but it need not end the conversation with the founder. Several can be fixed later (a cap table cleaned, a co-founder recruited), so say what would have to change and leave the door open.
Willingness to dilute and willingness to accept a lock-up are promises, and they bind only once they are written into the shareholders’ agreement. At the screen you are testing whether the founder will make the promise at all.
The six filters, in Twenty minutes
What survives the blockers is judged on six filters, each a pass or a fail with no score attached. Take them in order and write one line per filter with the evidence that settled it, because those lines become the agenda if the case passes.
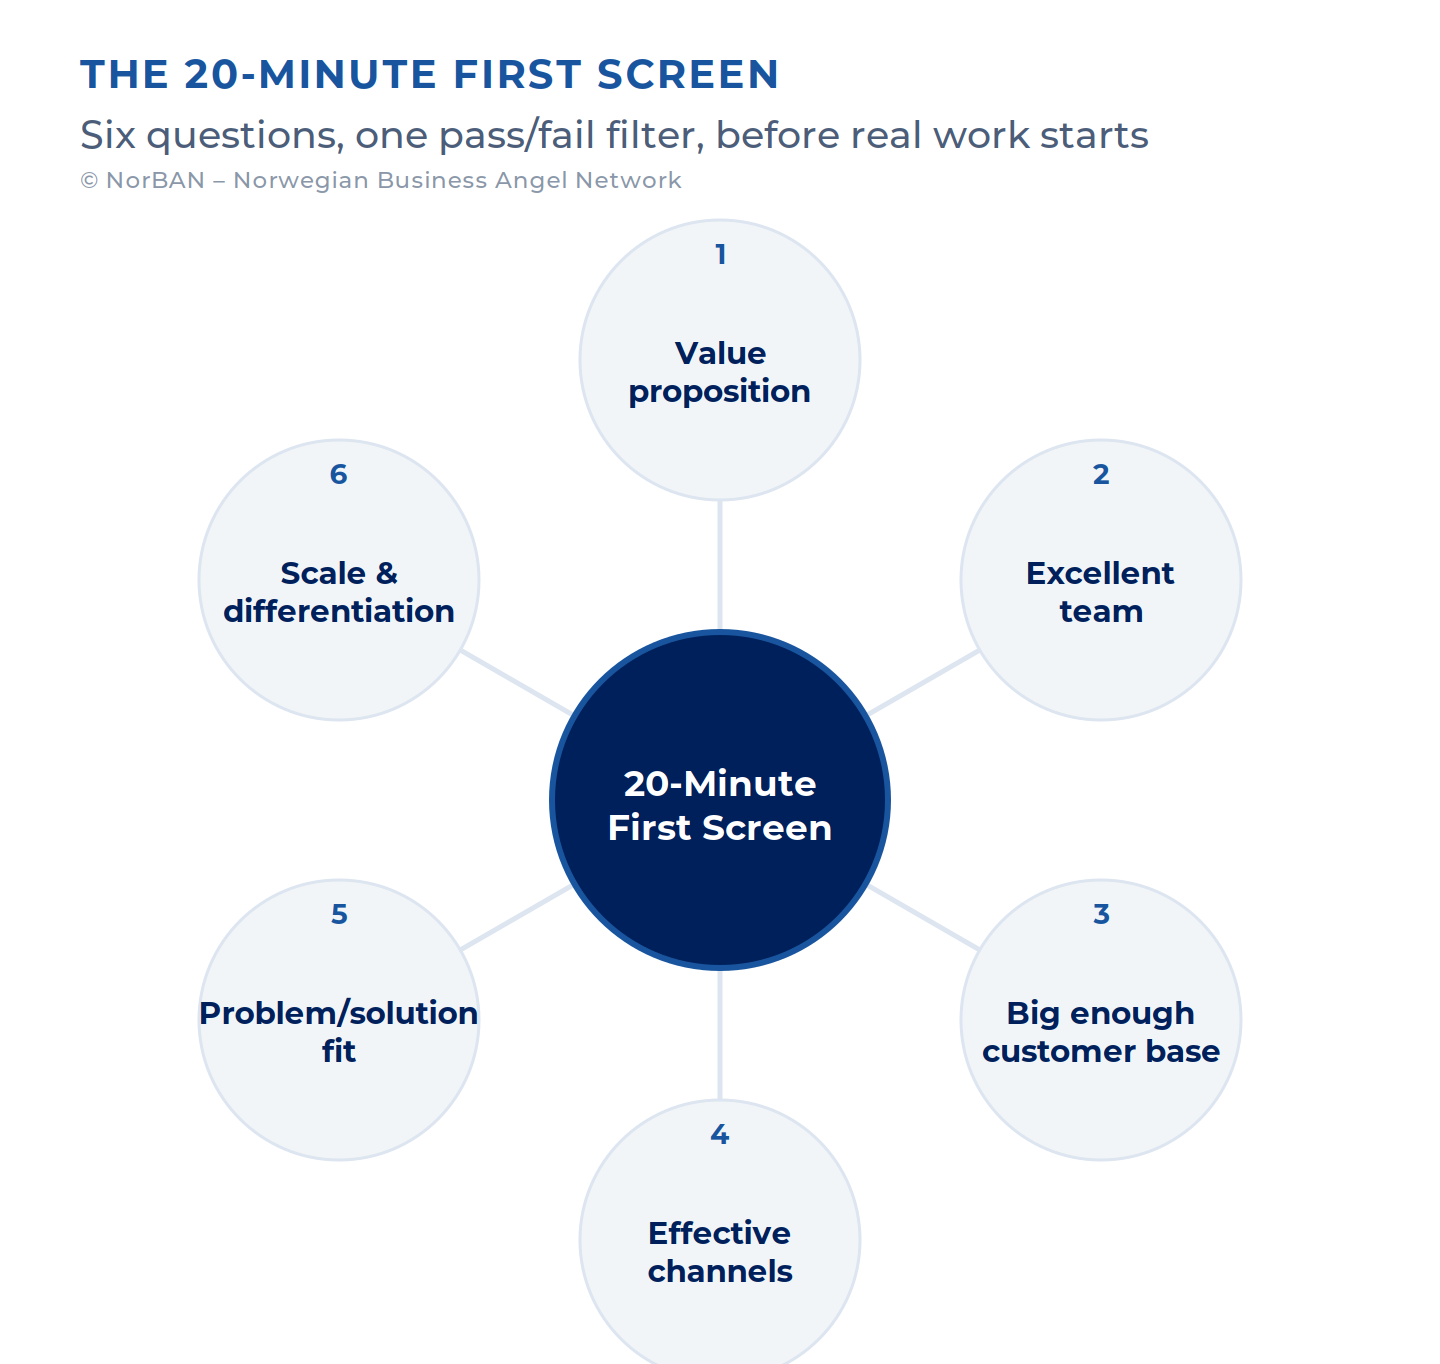
| Filter | What passes, and what fails |
|---|---|
| Value proposition | One sentence naming who has the problem, what it costs them, and what changes when they buy. Fails when the pitch describes the technology and never names the buyer’s pain. |
| Excellent team | Founders with domain history, a credible split of commercial and technical work, and evidence they have done hard things before. Fails on impressive CVs with no relevance to this market, or a team assembled around the funding rather than the problem. |
| Big enough customer base | A defined segment large enough that a plausible share of it is a real business. Fails on a market size taken from an analyst’s total for the whole category. |
| Effective channels | A route to the customer that has been used at least once, at a cost the business model can absorb. Fails on “We will do content marketing and partnerships” with no evidence either has been tried. |
| Problem/solution satisfaction | Customers who have bought, renewed or told you the current alternative is worse. Fails on enthusiasm from people who will never be invoiced. |
| Scale and differentiation | A reason growth gets cheaper with volume, and a reason a competitor with more money cannot simply copy it. Fails on growth that costs the same per customer forever, or a difference any incumbent could add in a quarter. |
Twenty minutes is enough for this. Read in order, and stop as soon as a stage settles the case:
- The blockers. Cap table, the ask, the price, and the founder’s stance on governance and lock-up.
- The six filters, one line each: pass, fail or unresolved, and the evidence.
- The numbers, only far enough to see whether they are consistent with each other and with the slides before them. Anything that needs a spreadsheet waits for a second session, which is all a pass leads to.
Customer base and channels remove most of the optimistic cases, because both are checkable in a first pass and neither can be rescued by conviction. Problem/solution satisfaction separates the strongest cases. A company with three customers who have paid twice is a different proposition from a company with thirty conversations.
Where you spend the minutes depends on what you know. With a sector background, scale and differentiation is where your judgment is worth most, and where a founder cannot get past you with vocabulary.
Without one, stay on customer base, channels and paying customers, which anyone can check. Leave the technology for the second session, or for a co-investor who knows it.
Scoring without false precision
A score is for consistency. The same criteria go on the tenth case as on the first, and you keep a record to re-read when the company comes back a year later. It does not produce a valuation (verdsettelse), a probability or a ranking that means anything to two decimal places.
Keep the scale coarse. Score each criterion from 1 to 7, wide enough to distinguish and narrow enough to resist invention. Hard gates, answered yes or no, are the right shape for the blockers above.
Score the areas separately before you form a view of the whole. A short questionnaire of four areas with three questions each (market, product, entrepreneur and core team, economy), answered no, maybe or yes. Three good areas and one failed one tells you more than an average would, and tells you where the first meeting starts.
Score yourself too. The companion instrument asks whether you have the time, the engagement and the relevant expertise for this company, and whether a good exit opportunity looks realistic within four to six years. If you cannot support the case, decline it however strong it is.
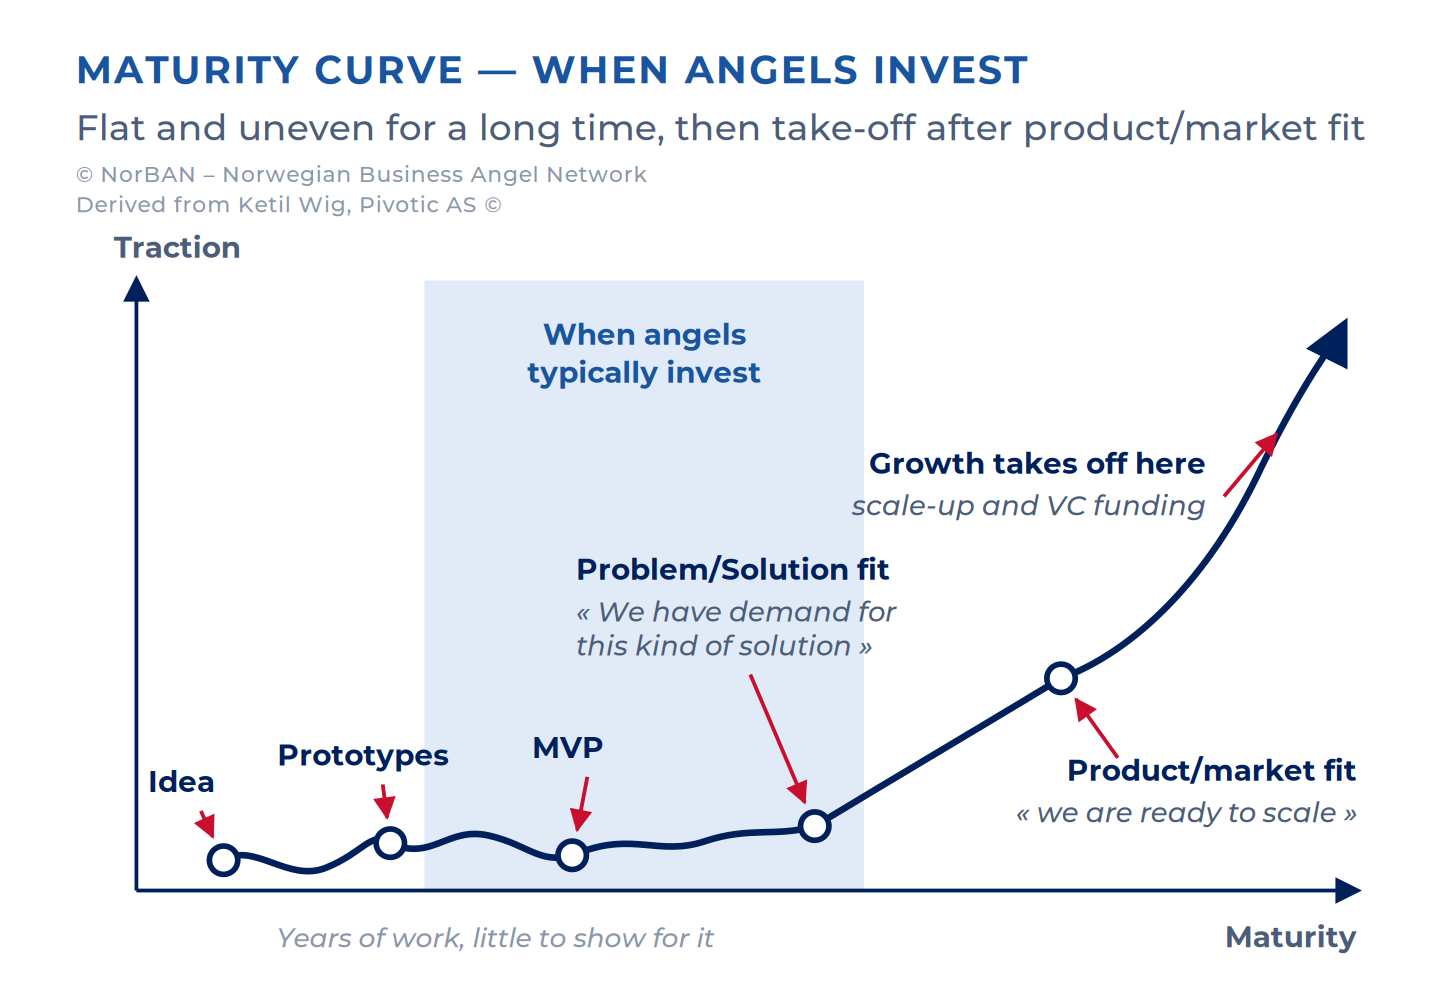
The bar depends on stage. An early startup has to defend a return of more than 50x to be interesting, while a scale-up might be interesting at a likely 10x. Most positions in a portfolio return less than the money put in, so screen an idea-stage case harder than a revenue-stage one.
The relay-baton question
The angel is often the first professional money after friends and family, and the money after yours decides whether your position ever becomes worth anything. The question at this point is who takes the relay baton (stafettpinnen) in the next financing round.
- Is this a business the next round will fund? Venture funds, strategic buyers and public co-investors all have entry criteria, and a company that cannot meet any of them within its runway is one you will be asked to refinance yourself.
- Does the founder know who that next investor is and what would have to be true to interest them, or has the plan stopped at this round?
Look for the answer in the deck before you look for it in the founder. A slide naming the next investor and the milestones that interest them settles it; a deck with no round after this one leaves it unresolved for the meeting.
A case can pass all six filters and fail this one. It is a legitimate decline, and one of the few worth explaining in full, because timing is often the reason.
The pass and the decline
A pass gets the founder a meeting and a full, critical read of the pitch deck (pitchpresentasjon). Founders reasonably read enthusiasm as intent, so say plainly that it does not get them a term sheet, a price indication, or an expression of interest they can quote to other investors.
Take the screen’s output into that meeting as a written list. It is the agenda of the first conversation and the first draft of the diligence scope:
- which filters passed, and on what evidence
- which are unresolved, and what would settle each
- the relay-baton answer, if the deck gave one
A fail should be fast and final in the same message, and it should name the criterion that closed it. Do not soften it into a maybe. Say if and when a changed circumstance would make the case worth revisiting, because founders talk to each other and a network that declines clearly keeps being sent deals.
The criteria are the same for every angel. How you run the routine changes with experience:
- A first-time angel writes every screen down, blockers first, and sends the decline the same day. The written record is what makes the tenth screen consistent with the first.
- An experienced angel can decline in one sentence naming the criterion, and save the full explanation for the relay-baton fail, where the founder can act on it.
- An angel building a syndicate keeps one sheet per case and shares it, so a company is screened once and declined once, and comes back to the group with a record of why.