
What a first screen is for
Most of what reaches you should not even get past the first ten minutes of the screen. The first screen is the opening step in your decision process and determines which cases deserve further work.
- Incoming case
- Prescreening
- Screening and analysis
- Term sheet
- Due diligence (selskapsgjennomgang)
- Shareholders’ agreement and investment agreement
- Signing
- Kick-off and the 100-day plan
Before the term sheet, you are deciding which cases warrant further work. The screen is the quickest check you can make alone, without asking the founder for anything.
A low single-digit share of applicants ends in an investment. The numbers say declining an investment is the normal outcome, so build a routine that expects to decline most companies you review. In the standard group funnel described by the Angel Capital Association, about 10 to 25 percent of applicants reach the screening or presentation stage, but 25 to 50 percent of the companies that get as far as due diligence end up being funded.
Assess the business against your criteria, using the available evidence to distinguish weaknesses in the company from weaknesses in how the founders have presented it.
Pitch competitions show the same pattern. A polished pitch can represent a company that never gets off the ground, while a hesitant speaker may be building something with far greater potential.
Hard blockers: what ends the screen immediately
Choose which blockers to apply and check them first. Any one of them can end the screen before you spend the full twenty minutes.
| Blocker | What would stop you proceeding on the present evidence |
|---|---|
| Unwilling to work with angels | Wants money without governance, reporting or advice, and treats questions as intrusion. Angel capital comes with angel involvement, that is not negotiable. |
| Unwilling to share and dilute | Refuses to go below a fixed ownership share, or talks about “giving away” equity. The round cannot be priced, and neither can any future round. |
| Unwilling to accept lock-up | Wants freedom to sell or exit ahead of the other shareholders. Lock-up is the commitment the rest of the cap table is buying. |
| Valuation expectation out of range | A price that only clears if everything goes right and nothing costs anything. Diligence cannot argue a founder down from a number that is identity rather than analysis. |
| Team | A single founder with no plan to fill the gaps, or a team that cannot describe its own division of labor. At this stage you are underwriting execution and nothing else. |
| Case | No defensible activity, or an idea that is a feature of someone else’s product. The problem is the business itself, however it is presented. |
| Governance | A broken cap table, dormant shareholders holding large blocks, or unresolved past disputes. Every future round has to renegotiate the past before it can price the future. |
| Title and patent | The company does not own its core technology, code or brand. Ownership defects are slow and expensive to repair, and some cannot be. |
| Diligence access | Unwilling to open books, contracts or the register to scrutiny. A no now will be a no when your money is at risk. |
| Finance | No control of cash, no budget, or a funding need the round on offer cannot reach. An underfunded round gives you a shorter runway and the same problem again. |
A blocker ends the screen, but it need not end the conversation with the founder. Several can be fixed later (a cap table cleaned, a co-founder recruited), so say what would have to change and leave the door open.
Willingness to dilute and willingness to accept a lock-up are promises, and they bind only once they are written into the shareholders’ agreement. During screening, establish whether the founder is willing to make those commitments.
The six filters, in twenty minutes
Record Pass, Fail or Unresolved against each filter, with the evidence behind it. An unresolved point needs follow-up; where a failed condition can be repaired, record what must change before you reconsider.
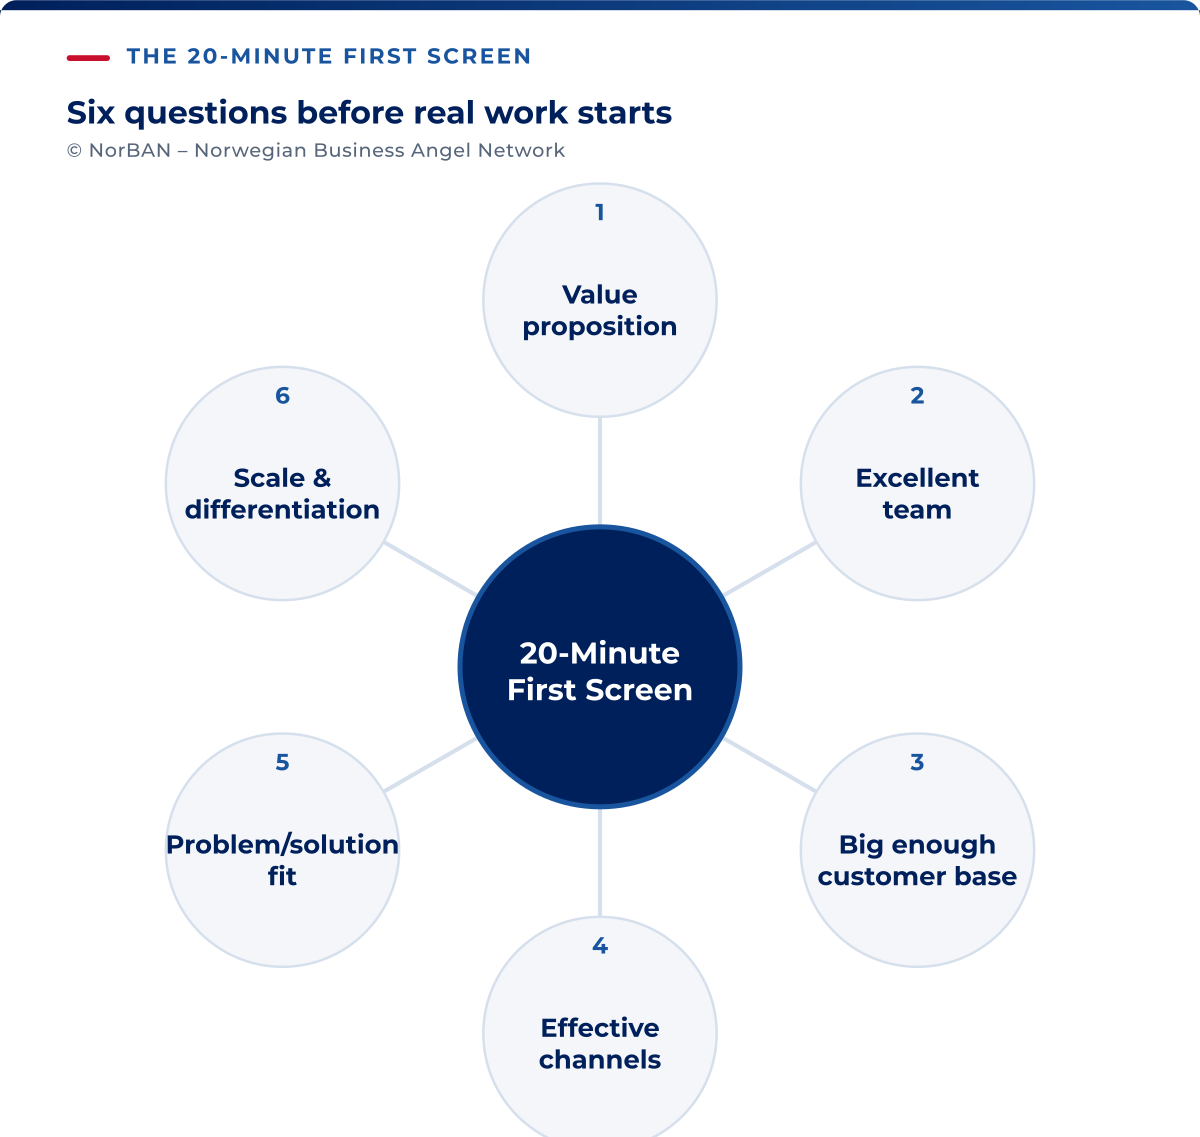
For cases that survive the blockers, work through the six filters in order. The evidence and unanswered questions become the agenda for the next conversation.
| Filter | What passes, and what fails |
|---|---|
| Value proposition | One sentence naming who has the problem, what it costs them, and what changes when they buy. Fails when the pitch describes the technology and never names the buyer’s pain. |
| Excellent team | Founders with domain history, a credible split of commercial and technical work, and evidence they have done hard things before. Fails on impressive CVs with no relevance to this market, or a team assembled around the funding rather than the problem. |
| Big enough customer base | A defined segment large enough that a plausible share of it is a real business. Fails on a market size taken from an analyst’s total for the whole category. |
| Effective channels | A route to the customer that has been used at least once, at a cost the business model can absorb. Fails on “We will do content marketing and partnerships” with no evidence either has been tried. |
| Problem/solution satisfaction | Customers who have bought, renewed or told you the current alternative is worse. Fails on enthusiasm from people who will never be invoiced. |
| Scale and differentiation | A reason growth gets cheaper with volume, and a reason a competitor with more money cannot simply copy it. Fails on growth that costs the same per customer forever, or a difference any incumbent could add in a quarter. |
Work through the checks in order within twenty minutes, stopping as soon as you have grounds for a decision:
- The blockers. Cap table, the ask, the price, and the founder’s stance on governance and lock-up.
- The six filters, one line each: pass, fail or unresolved, and the evidence.
- The numbers, only far enough to see whether they are consistent with each other and with the slides before them. Anything that needs a spreadsheet waits for a second session, which is all a pass leads to.
Customer base and channels remove most of the optimistic cases, because both are checkable in a first pass and neither can be rescued by conviction. Problem/solution satisfaction separates the strongest cases. A company with three customers who have paid twice is a different proposition from a company with thirty conversations.
Use your time according to your expertise. If you know the sector, focus on scale and differentiation, where you can assess the substance of the claims behind the terminology.
Without a sector background, focus on customer base, channels and paying customers, which anyone can check. Leave the technology for the second session, or for a co-investor who knows it.
Scoring without false precision
If the initial screen supports further work, use a scorecard to record the strengths, weaknesses and evidence gaps. Keep the same criteria across cases so you can explain why your assessment changed when new evidence arrived.
An optional scorecard
Rate market, product, founder and team, and economics separately. If you use a 1–7 scale, define what its points mean before scoring and record the evidence for each judgement. Where evidence is missing, mark the criterion unresolved rather than assigning an invented middle score.
Keep failed screening conditions visible. A high score elsewhere does not answer an unresolved ownership issue or replace a required legal check. Use the scorecard to prepare questions for the meeting; do not turn its average into a valuation or a probability of success.
Assess your own fit alongside the company: the time you can give, your engagement and relevant expertise. Test the proposed exit route too. A four-to-six-year scenario is an assumption to examine, not a forecast of when your money will return.
The return case depends on stage and the capital still needed. The illustrative hurdles of more than 50x for an early startup and 10x for a scale-up describe scenarios to test, not expected returns or a universal screening rule. Model later dilution before relying on either.
The relay-baton question
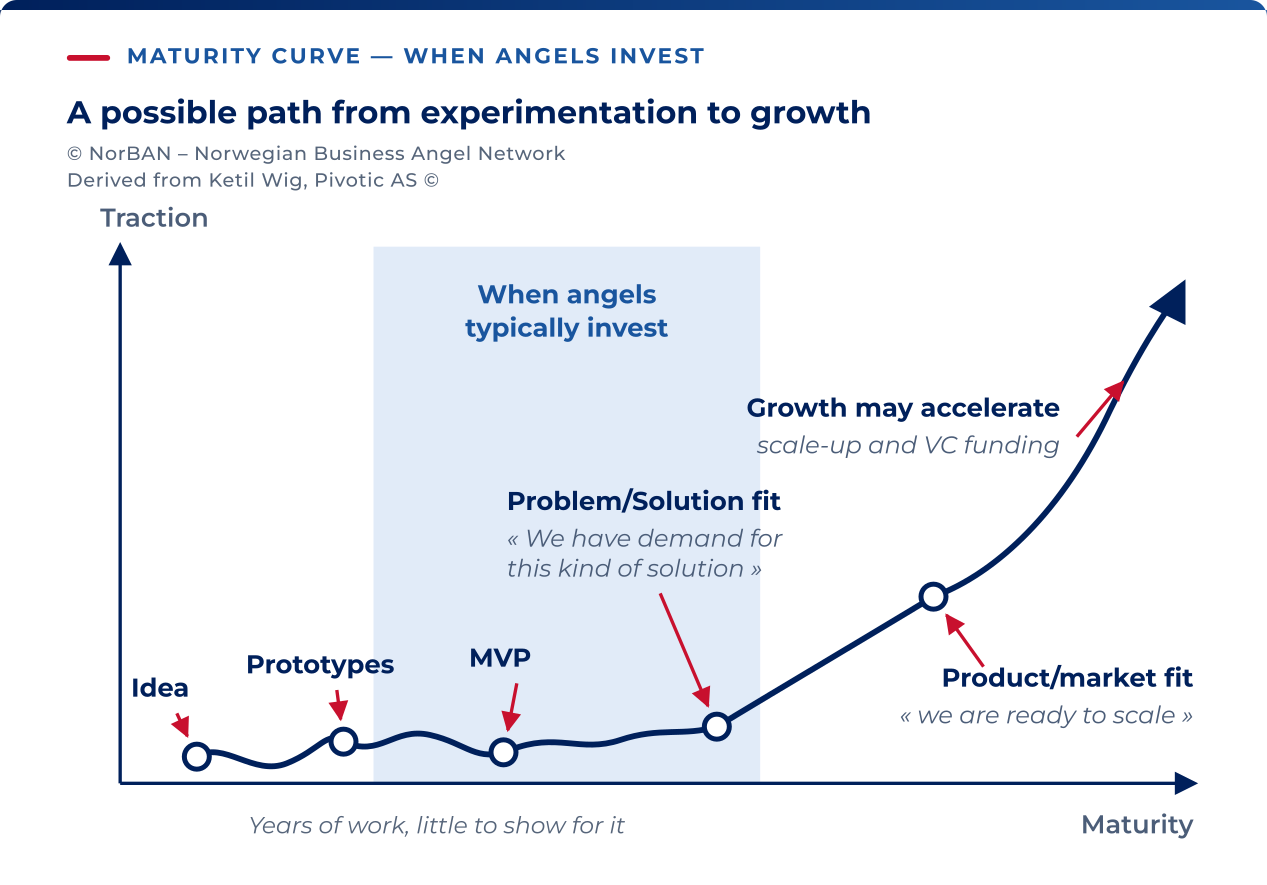
The angel is often the first professional money after friends and family, and the money after yours decides whether your position ever becomes worth anything. The question at this point is who takes the relay baton (stafettpinnen) in the next financing round.
- Is this a business the next round will fund? Venture funds, strategic buyers and public co-investors all have entry criteria, and a company that cannot meet any of them within its runway is one you will be asked to refinance yourself.
- Does the founder know who that next investor is and what would have to be true to interest them, or has the plan stopped at this round?
Check the deck for an answer before asking the founder. A slide naming the next investor and the milestones that interest them settles it; a deck with no round after this one leaves it unresolved for the meeting.
A case can pass all six filters and fail this one. It is a legitimate decline, and one of the few worth explaining in full, because timing is often the reason.
The pass and the decline
A pass gets the founder a meeting and a full, critical read of the pitch deck. Founders reasonably read enthusiasm as intent, so say plainly that it does not get them a term sheet, a price indication, or an expression of interest they can quote to other investors.
Take the screen’s output into that meeting as a written list. It is the agenda of the first conversation and the first draft of the diligence scope:
- which filters passed, and on what evidence
- which are unresolved, and what would settle each
- the relay-baton answer, if the deck gave one
Send a prompt, clear decline that names the criterion the case failed. Avoid wording that leaves the decision uncertain. Say if and when a changed circumstance would make the case worth revisiting, because founders talk to each other and a network that declines clearly keeps being sent deals.
The criteria are the same for every angel. How you run the routine changes with experience:
- A first-time angel writes every screen down, blockers first, and sends the decline the same day. The written record is what makes the tenth screen consistent with the first.
- An experienced angel can decline in one sentence naming the criterion, and save the full explanation for the relay-baton fail, where the founder can act on it.
- An angel building a syndicate keeps one sheet per case and shares it, so a company is screened once and declined once, and comes back to the group with a record of why.