
What due diligence is for
Due diligence (selskapsgjennomgang) is verification. It confirms that what the founders told you in the pitch, the meetings and the model is true, complete and documented. Screening and analysis established your interest in investing. Diligence tests whether the evidence supports that decision. It sits at a fixed point in the decision sequence:
- Incoming case
- Prescreening
- Screening and analysis
- Term sheet
- Due diligence
- Shareholders’ agreement (aksjonæravtale) and investment agreement
- Signing
- Kick-off and the first 100 days
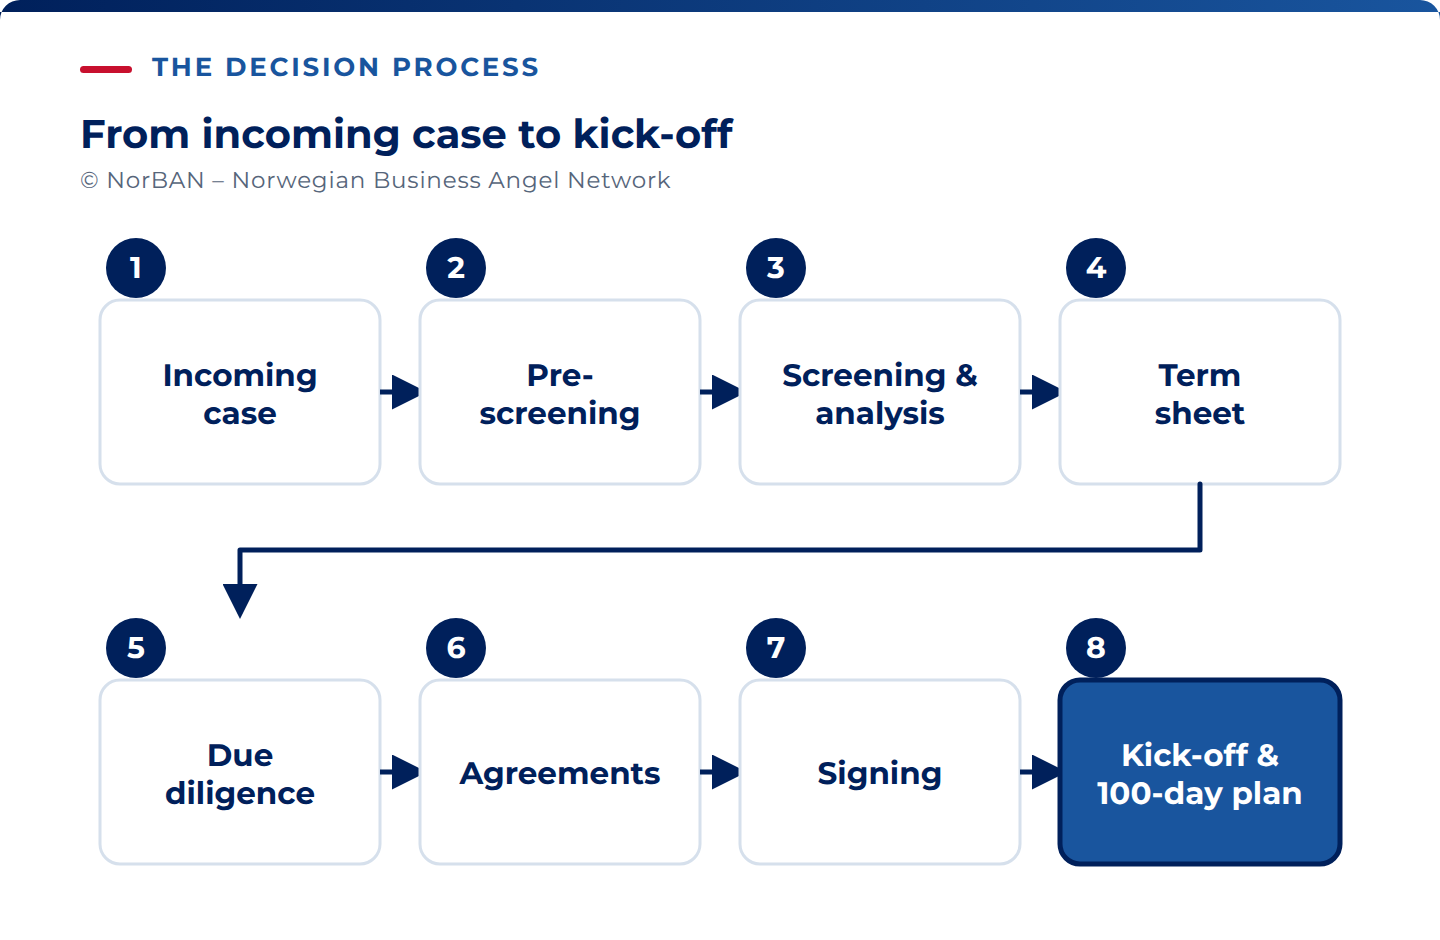
Agree price and structure in principle, then complete diligence before an unconditional commitment to invest. If you sign an investment agreement first, have counsel specify the diligence condition and its consequences. Use findings to negotiate terms and identify repairs the company must complete.
Why the stakes are asymmetric
Once the money is paid in, there is very little chance of getting it back. There is no refund mechanism for a minority holding in an unlisted company, and no buyer for it either, so the verification belongs before the payment.
Enthusiasm for the founders can distort the assessment. An investor who has decided they like the founders runs diligence to confirm the decision, reads a missing document as an administrative delay, and treats an evasive answer as a personality trait. If you notice yourself explaining away findings, hand the workstream to someone who has not met the founders.
Scaling the work to the investment
The published evidence on effort is old but consistent. Wiltbank and Boeker’s 2007 study of US angel groups found a median of 20 hours of diligence per investment. Angels who reported more than 40 hours saw a 7.1x multiple, those below 20 hours 1.1x, against 2.6x for the sample as a whole.
NESTA’s 2009 UK study found the same 20-hour median and significantly fewer failures where at least 20 hours were spent. Both are correlations on deals the investors chose themselves, so the studies do not establish whether spending more hours caused the better returns. In those studies, investors who spent less time on diligence were more likely to lose money.
Depth should match exposure, and in Norway the investment sets the scale. NorBAN’s figures put most angel tickets between 0.5 and 2 MNOK, round-filling tickets around 100,000 kroner, and only a small minority at 2 to 5 MNOK or more.
A 100,000-kroner ticket does not justify forty hours of your own diligence, and an acquisition-grade process on a pre-revenue company is the wrong match. Match the time you spend to your exposure and role in the round. Do the “never skip” items yourself, whoever else is working on the deal.
| Situation | Proportionate depth |
|---|---|
| Small direct ticket, pre-seed, alongside a lead you trust | Read the lead’s findings and verify the items that decide your own downside. Never skip the cap table, the share register, founder commitments, and outstanding options and convertibles. |
| Lead-sized position, seed, board seat expected | The full four-workstream process, with external counsel on the legal stream. Never skip anything in the row above, plus customer references and the IP chain. |
| Follower in a syndicate | The workstream allocated to you, in full, plus a read of every other workstream’s findings. Never skip the lead’s assumptions that you would not have made yourself. |
| Follow-on into a company you already hold | Focus on what has changed since the last round and on the previous plan’s promises. Never skip a reforecast against the milestones you were sold last time. |
At the earliest stage the most useful diligence is often a working session. Sit with the founders on the two or three issues that decide the case, and treat their handling of the questions as evidence in its own right.
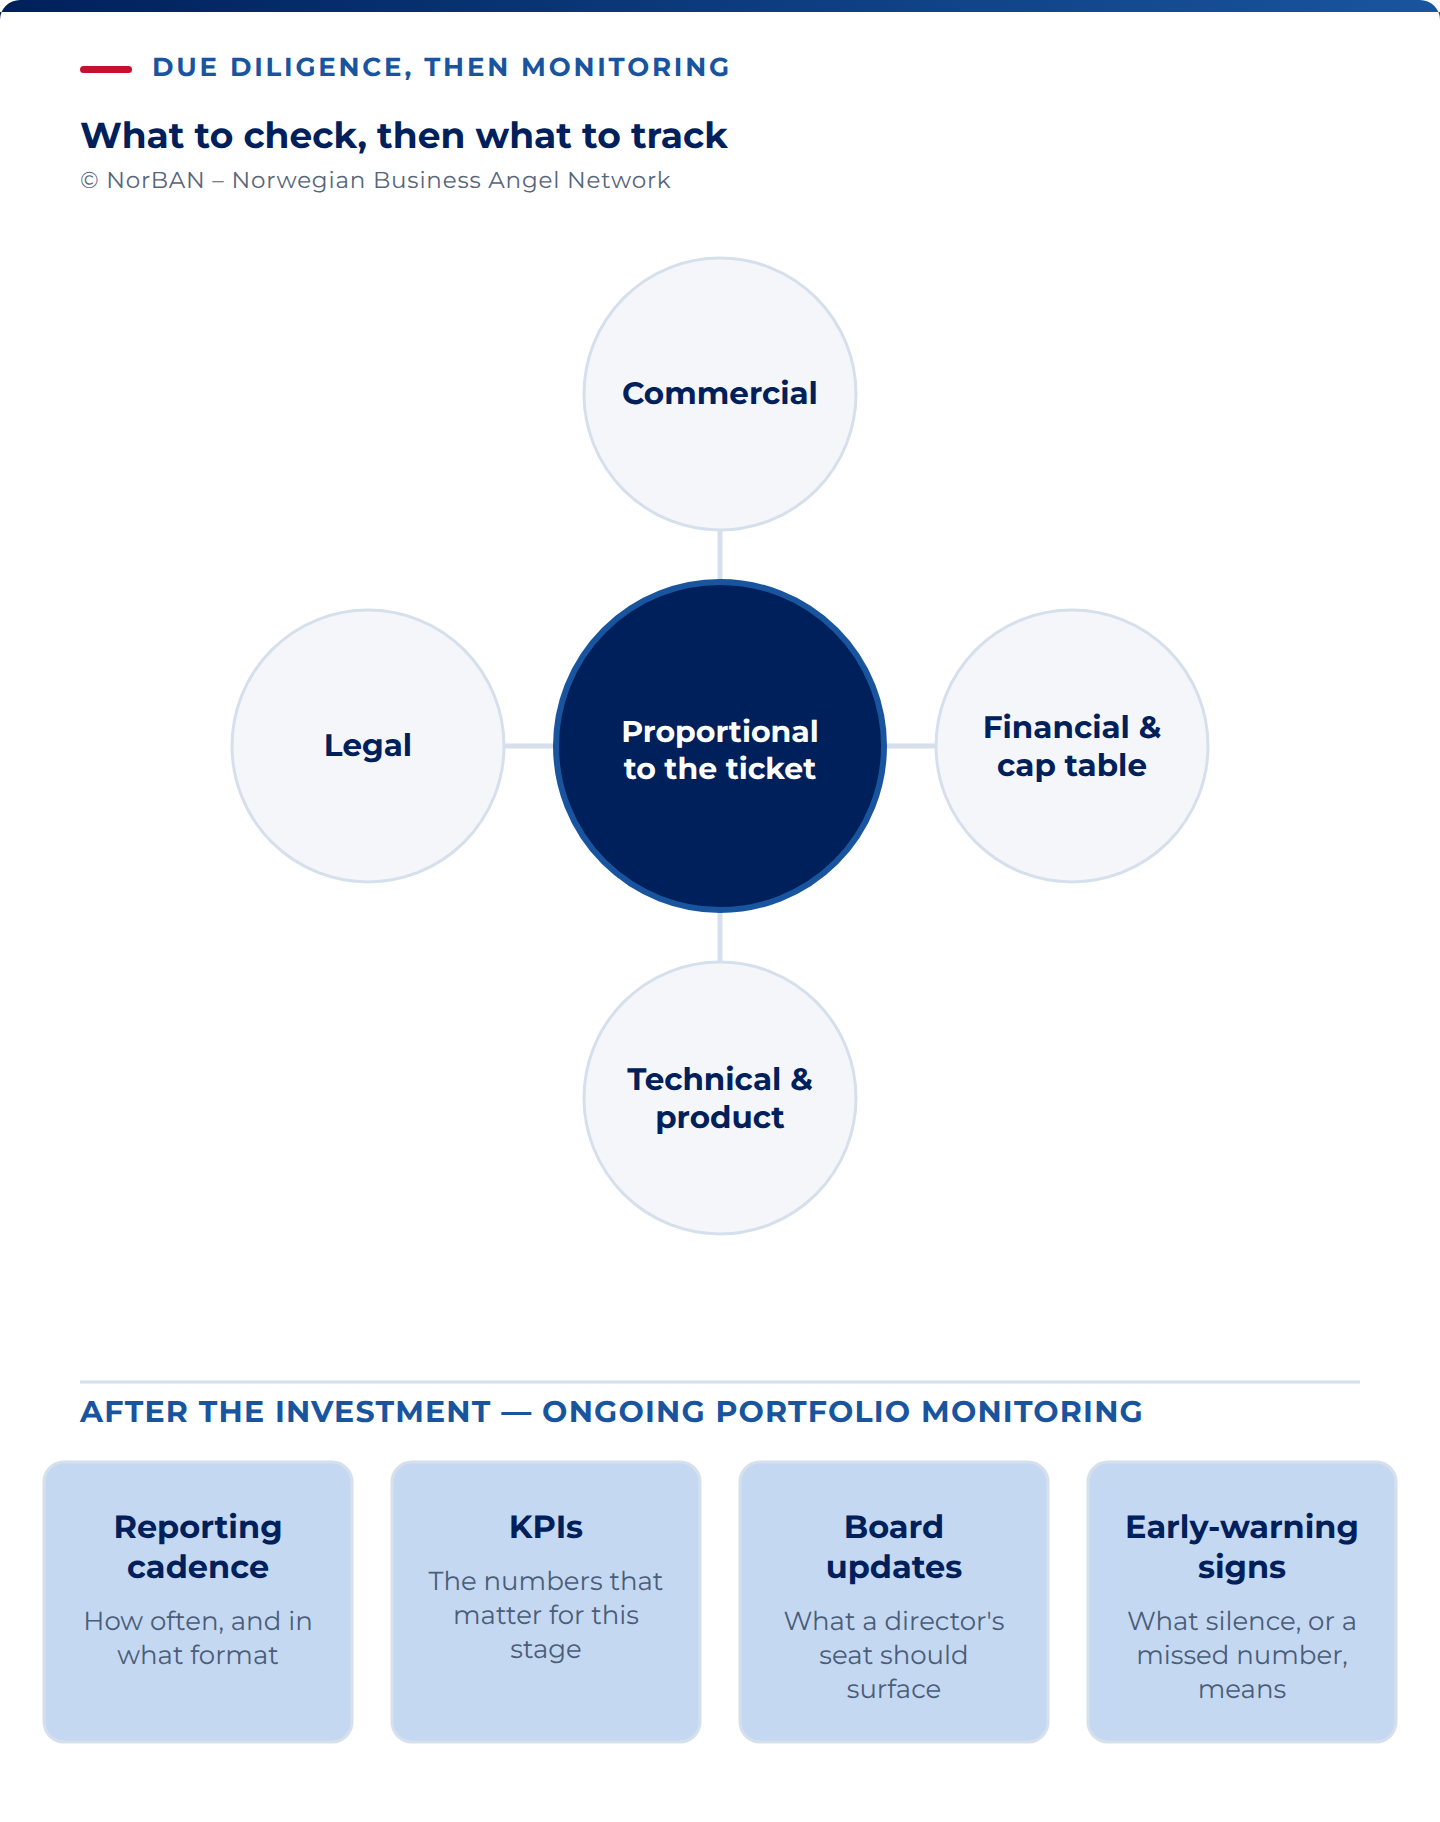
The four workstreams
Give each stream to a competent reviewer. Complete diligence when the findings address every material claim behind the investment decision, with unresolved matters explicitly recorded.
| Workstream | The question it answers |
|---|---|
| Commercial | Is there a market, does the product win in it, and are the customers real? |
| Financial | Do the numbers reconcile to the accounts, and how long does the cash last? |
| Legal | Does the company own what it says it owns, and can the deal be executed as agreed? |
| Technical | Does the technology work, can it scale, and who built it? |
Dividing the work in a syndicate
Group diligence is normally shared between the investors, each taking the areas where they have relevant knowledge, expertise or contacts, with a lead investor who deals directly with the company. UKBAA describes this as standard group practice.
The Angel Capital Association adds a condition: at least one member of the group needs real experience of the domain, and that person leads on it.
In a syndicate of NorBAN members the lead also chooses the instrument and legal framework, engages counsel, sets up the investment vehicle, and runs signing and follow-up.
Agree each member’s responsibilities before sending the request list. This avoids duplicate work and missed checks.
- A first-time angel follows. Take one workstream you can actually check, do it in full, and read every other stream’s findings. Verify the share register, the fully diluted cap table and the founders’ employment and lock-up terms yourself, because those determine what you actually buy.
- An experienced angel leading the round allocates the workstreams, holds the single findings list, and decides when the process is finished. On a lead-sized position, put external counsel on the legal stream.
- An angel with a sector focus takes the commercial or technical stream in that domain, because the group needs one member with real experience of it and that member leads on it.
- An angel building a syndicate writes down the split of workstreams and who holds the findings list, so every member knows what they own.
Whatever your role, compare the amount you were willing to invest before diligence with the amount you would invest now.
Timing: before the term sheet binds, or as a condition of it
There are two customary places to put the work. The difference is who carries the uncertainty while it runs.
The first is diligence after a term sheet or letter of intent, before any binding investment agreement. This preserves your optionality and gives the founders no certainty. It depends on the document saying expressly that it is not binding except for the clauses intended to bind (exclusivity, confidentiality, costs).
Norwegian contract law has no form requirement and no statutory category of non-binding term sheet. A document binds if its wording and the circumstances show the parties intended to be bound, whatever it is called, so the wording has to be right before you sign anything.
The second is diligence as a condition in a signed investment agreement. The deal is agreed, completion depends on the outcome, and the founders can plan. The withdrawal right then has to be drafted objectively (which findings, of what materiality, release you) or it becomes an option in disguise and will be argued about.
An early-stage diligence process usually involves a short series of meetings. A typical angel diligence runs to about four meetings, two with the founders and two among the investors. That is enough for a small syndicate and a simple company; a company with customers, employees and code needs the full request list.
Use findings to adjust the price, set conditions that must be met before closing, or allocate risk in the agreements. A finding may also justify ending the process before committing money.