
The AS and the rules it lives under
Most Norwegian startups use a private limited company (aksjeselskap, AS). The Companies Act (aksjeloven) governs its general meeting (generalforsamling), board (styret) and share capital.
Ownership is recorded in the company’s share register (aksjeeierbok). Every AS must keep one, the board is responsible for it (aksjeloven § 4-5), and anyone may read it (§ 4-6). Since 1 February 2025 the company must as a rule send an electronic copy by email, free of charge, within three business days of a request.
The company cannot refuse access; the regulation‘s objective-grounds test (saklig grunn) only concerns delivery by other channels. Read the register before investing to check the current ownership against the cap-table slide.
Keep the transfer documents alongside the register. For existing shares, rights generally run from entry or a notified and documented acquisition not blocked by transfer restrictions (§ 4-2). Distributions and new-issue pre-emption are exceptions; until rights pass, the seller may exercise them.
The company must update the register without delay unless consent or pre-emption prevents it (§ 4-7). New shares follow § 10-11.
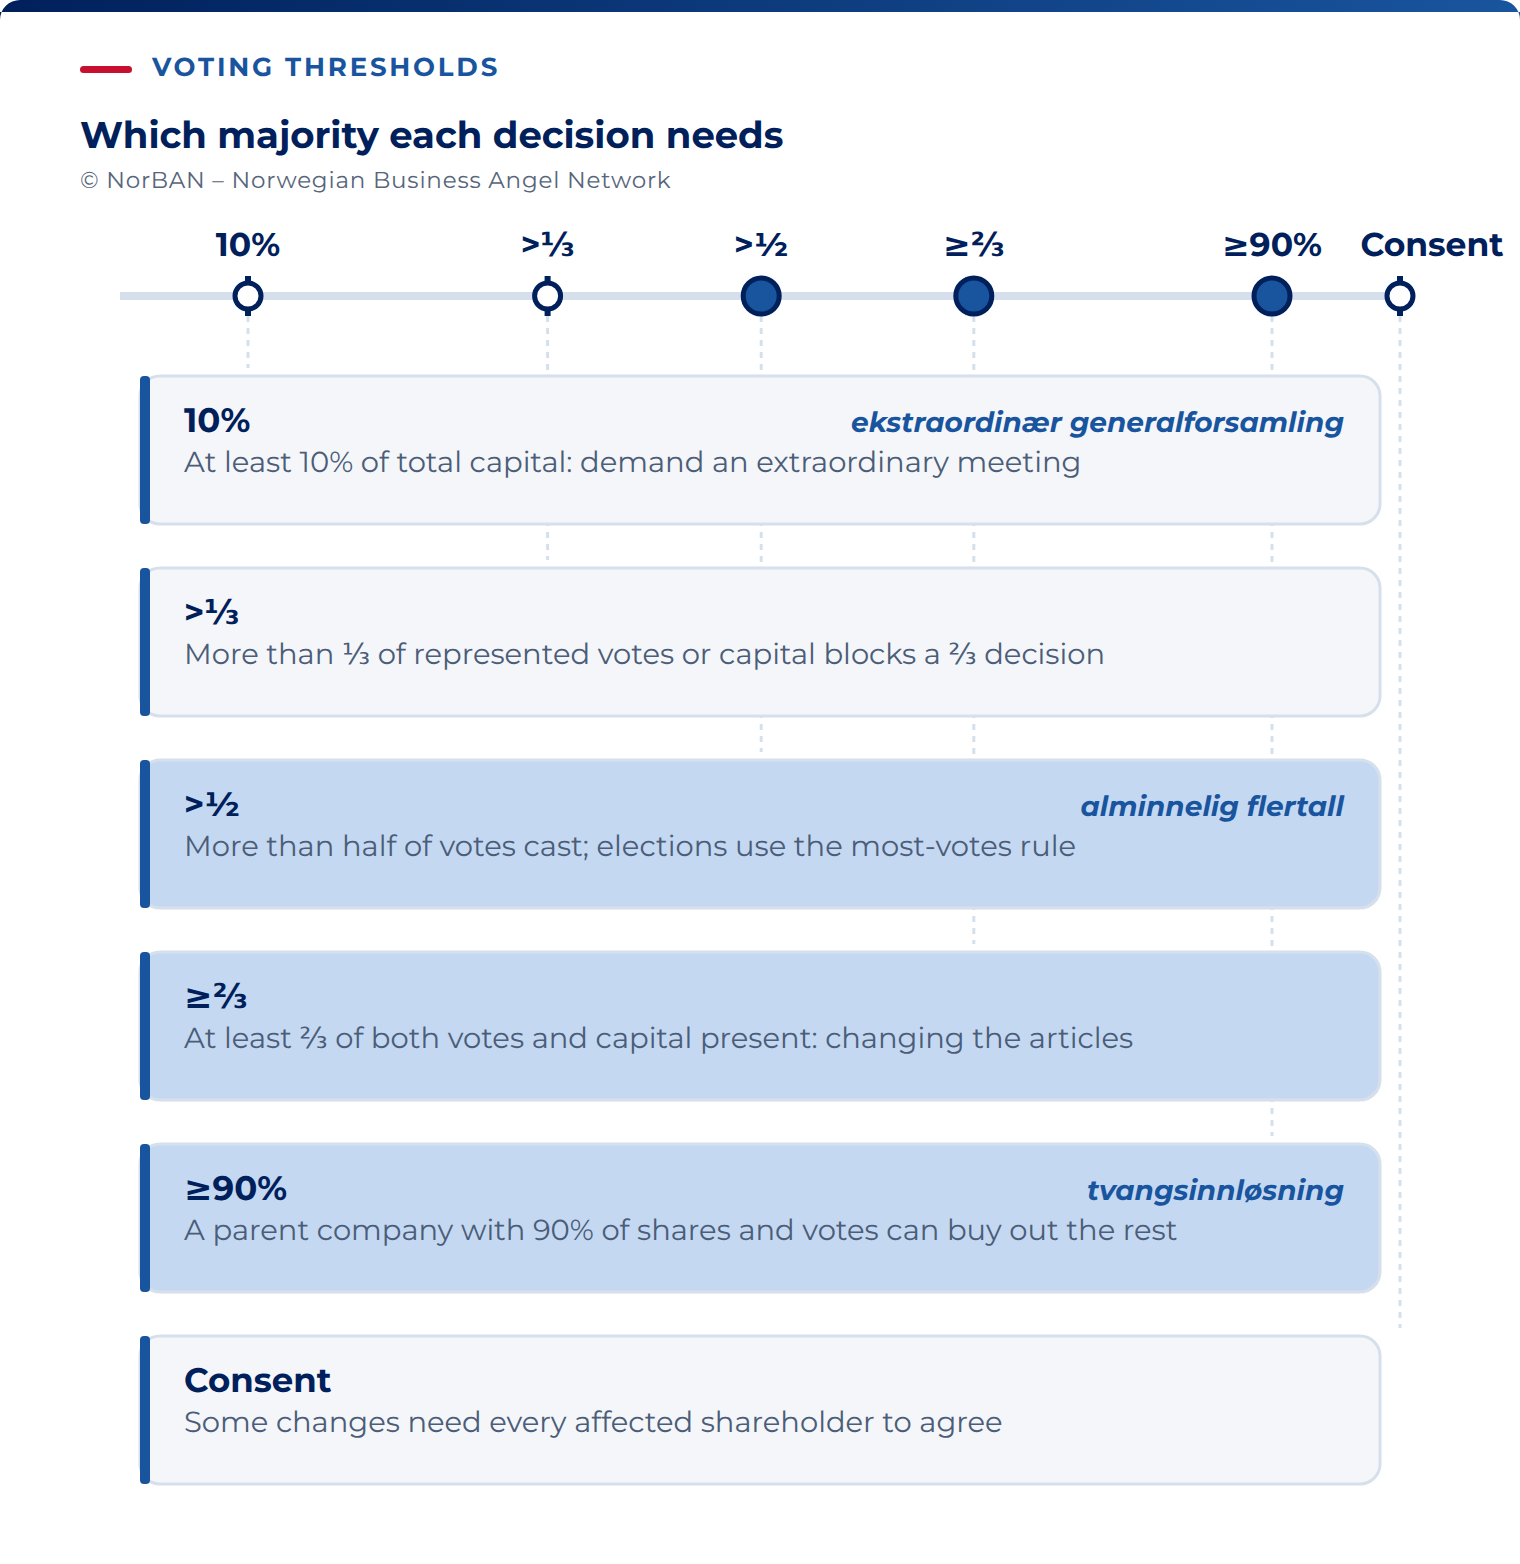
The ownership-threshold ladder
Ordinary decisions count votes cast; article amendments also count capital represented. An extraordinary-meeting demand uses total share capital, while an investigation proposal uses capital represented. For compulsory acquisition, count both the shares and the corresponding votes held by the qualifying corporate parent.
| Holding | What it enables or blocks | Statute |
|---|---|---|
| At least one tenth | Of total capital: demand an extraordinary meeting or petition for a higher dividend. Of capital represented: support an investigation (gransking) proposal, after which any shareholder can petition the court within one month | § 5-6, § 5-25, § 8-4 |
| More than one third of votes or capital represented | Blocks amendments to the articles of association, new share issues, mergers, demergers and voluntary liquidation | § 5-18 |
| More than half of the votes cast | Carries ordinary decisions, including approval of a board-proposed dividend; elections are won by the candidates with the most votes | § 5-17, § 8-2 |
| Two thirds of votes cast and capital represented | Amends the articles of association, resolves a capital increase, sets aside existing shareholders’ pre-emptive rights, and resolves mergers and liquidation | § 5-18, § 10-5 |
| At least nine tenths of shares and corresponding votes, held by a parent company | Compulsory acquisition of the minority, with a mirror right for each minority shareholder to be bought out | § 4-26 |
An angel-sized stake falls below all but the first of these thresholds. A single angel rarely reaches a tenth; a syndicate acting together often does, and a syndicate with more than a third of the votes can block the decisions that matter most.
Compulsory acquisition (§ 4-26) is a parent company’s right, at nine tenths or more of both shares and votes. An individual holding the same directly has no such right; an angel’s holding company can qualify as a parent.
What the law does not give a minority shareholder
The shareholders’ agreement (aksjonæravtale) must provide the protections you need beyond the statutory position below. Use these gaps to prepare your term negotiation.
- No tag-along (medsalgsrett) and no drag-along (medsalgsplikt). The Companies Act contains no provisions on either. If the majority sells, nothing in the statute takes you along.
- No board seat. The general meeting elects directors by the most votes (§ 5-17), subject to the articles and statutory exceptions such as employee representation. Negotiate any investor seat.
- No dividend entitlement. The general meeting resolves a dividend on the board’s proposal and cannot go above it (§ 8-2). A tenth of the capital can petition the court under § 8-4, but the rule is rarely invoked and gives no right to be paid.
- Thin information rights. At the general meeting you can require the board and the managing director to answer on the annual accounts, on matters put to the meeting and on the company’s financial position, unless the answer would cause the company disproportionate harm. A researched answer comes in writing within two weeks (§ 5-15).
- A slow escalation route. Beyond that, the remedy is an investigation (§ 5-25), backed by the rule that neither the general meeting (§ 5-21) nor the board and those who represent the company (§ 6-28) may give some shareholders an unreasonable advantage at the expense of others or of the company.
What to ask for depends on the size of your holding and the statutory rights it already gives you.
- An angel-sized first investment: tag-along, and reporting at a fixed frequency, so your information does not wait for the annual general meeting.
- A syndicate that reaches a tenth: the rights to call a meeting and to propose an investigation are already yours. Add a board or observer seat by agreement; the majority still elects the board.
- A holding above one third: you block every two-thirds decision, including the next share issue, and the rest of the cap table will want the terms of that veto written down.
How a share issue (emisjon) works
A round of financing is a capital increase. The Act fixes the sequence, which tells you when your money is at risk and when you own shares.
- The board proposes the increase with its supporting documents.
- The general meeting resolves it (aksjeloven § 10-1) by two thirds of the votes cast and of the capital represented, because the capital figure in the articles changes. The resolution states the amount, the nominal value and subscription price, who may subscribe, the deadlines for subscription and payment, and the rights attaching to the new shares.
- Existing shareholders have a pre-emptive right to subscribe pro rata in a cash issue (§ 10-4). A directed cash allocation may require that right to be set aside by the same two-thirds majority (§ 10-5). Other routes include transfer of subscription rights after the issue is resolved. Check the allocation.
- Subscription is made in the minutes or in a separate subscription document reproducing the resolution.
- Contributions must be paid and confirmed before filing. Cash can be confirmed by an auditor, a Norwegian or EEA financial institution, a lawyer or a state-authorised accountant; non-cash or set-off contributions require an auditor.
- The increase is notified to the Register of Business Enterprises within three months of the subscription deadline. Miss it and the resolution lapses and subscribers are repaid (§ 10-9).
- The new shares confer shareholder rights on registration, unless the resolution provides otherwise, and ordinary shareholder rights arise no later than registration (§ 10-11).
Until step 7 the shares you have paid for do not exist. Put the three-month deadline in your own calendar, and confirm the registration at Brønnøysundregistrene yourself.
Transferring shares
Read the articles of association before relying on the Act’s default transfer rules. The articles can make those rules more or less restrictive.
By default, acquiring a share requires the company’s consent. The board decides, and consent is deemed given if the acquirer has not been notified of a refusal within two months of the company being notified (§§ 4-15, 4-16).
Also by default, the other shareholders have a pre-emption right (forkjøpsrett) over shares that have changed owner (§ 4-19), exercisable within two months of the company receiving notice, at actual value where no price is agreed (§ 4-23).
The statutory right applies only after a sale has been concluded. It gives existing shareholders the right to take over an agreed deal, without entitling them to an offer before the sale. For anyone buying your shares it means up to two months of uncertainty after signing.
Transfer clauses in shareholders’ agreements and articles convert that after-the-fact right into an offer-first obligation, add the lock-ups and the tag- and drag-along rights the statute does not provide, and define what counts as a transfer.
The board and its duties
The board manages the company and supervises day-to-day management (§ 6-13). Under § 6-12, it must:
- Ensure the business is soundly organised.
- Prepare plans and budgets.
- Stay informed about the financial position.
- Ensure adequate control of the activities, accounts and asset management.
Those duties are personal. An angel accepting a board seat in a Norwegian AS takes on personal liability exposure as well as gaining access to information.
An observer has no director’s statutory office, but the arrangement can impose confidentiality and other duties, and participation in wrongdoing can create liability (§ 17-1(2)). An experienced angel with relevant sector background may be worth more to the company on the board, and takes the duties above with the seat.