
What a business angel is
A business angel (forretningsengel) is a private individual, or a group of individuals investing alongside each other, who puts personal capital into a startup in exchange for shares. Angels invest their own money; the professional investors that fund later rounds manage capital on behalf of others.
Angels sit between the founders’ friends and family and the venture funds, typically at the seed (såkorn) stage: after the idea has a company around it and before the company can carry an institutional round. Equity crowdfunding (folkefinansiering) fills part of the same gap, with many small investments and no investor at the table.
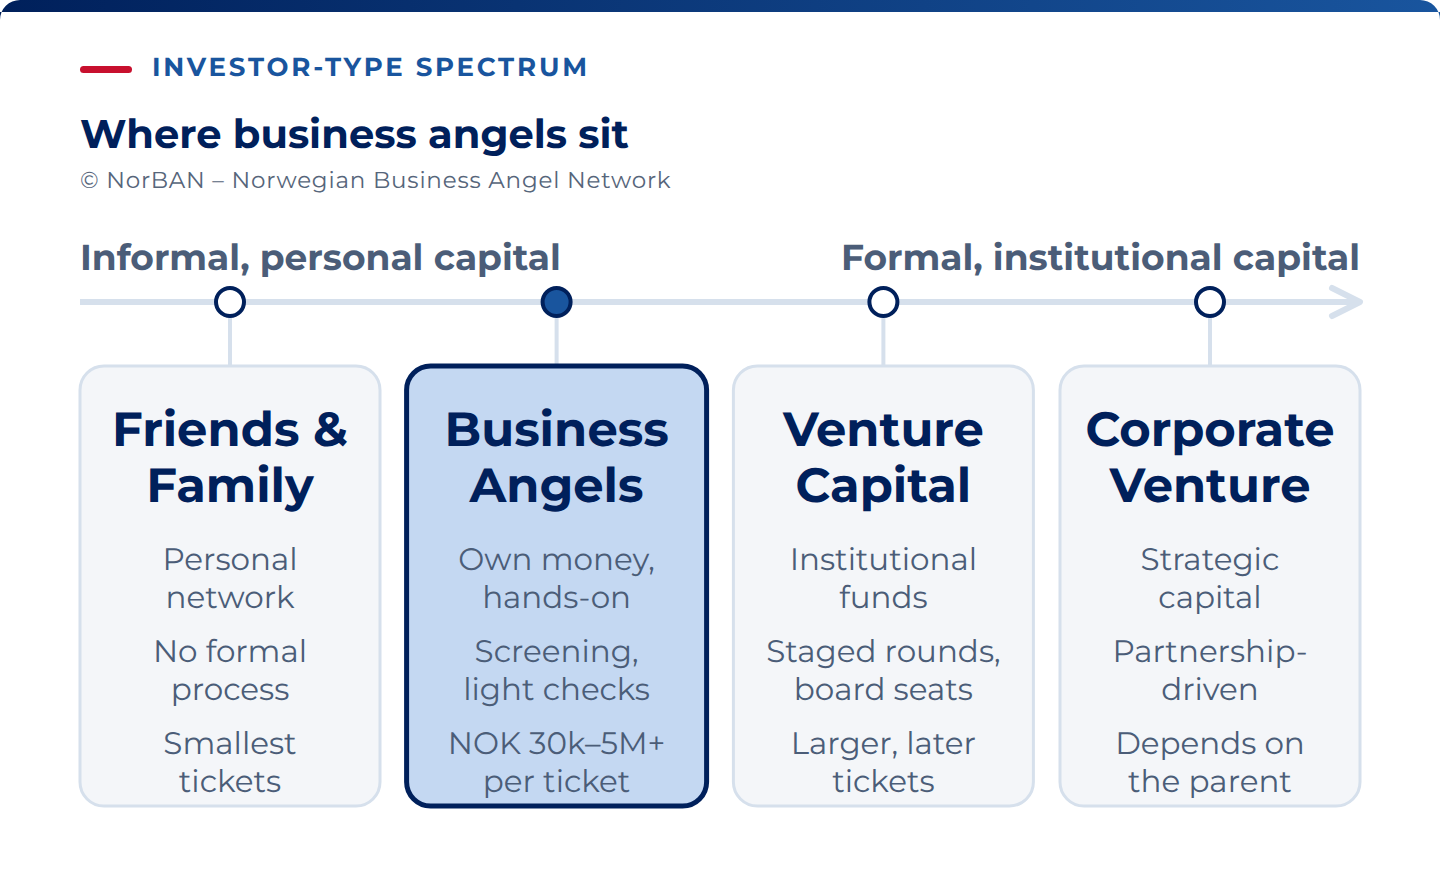
A five-digit investment in a single startup is enough to make you a business angel. The European average is close to that amount.
Across 39 countries, EBAN’s 2024 statistics compendium recorded EUR 1.22 billion of visible angel investment in 2024 from around 47,600 active angels, an average ticket of EUR 25,600 per angel per round.
Norway accounted for EUR 25.23 million of that, across roughly 700 angels and four angel networks. These are visible-market figures (investments made through networks and reported to them), so the real market is larger.
Menon’s registry-based 2010 report for the Ministry of Trade and Industry, counted around 2,400 angels holding stakes in around 4,500 companies, with an average holding of 18 per cent.
NorBAN’s published figures give the scale in kroner. Most tickets sit between 0.5 and 2 MNOK; round-filling tickets have a median around 100,000 kroner and the larger ones around 1 million, and only a small minority write 2 to 5 MNOK or more.
Nearly all Norwegian angels prefer pre-seed, few invest later than seed, and fewer than a third have capacity to follow on. Expect dilution if you are in the majority.
What you put in, and what you get back
You invest capital in exchange for ordinary shares or an instrument that converts into them. Most angels also contribute time, one of the few things they control, through board work, customer introductions, hiring help and experience of running a business.
You become a co-owner. There is no market in the shares of an unlisted Norwegian company, no daily price, and no right to have your money returned.
Your holding will be diluted by later rounds unless you pay to keep it. You are a minority shareholder in a company whose fate is decided by its founders, its customers and its next financing.
Most startups do not survive
Use SSB’s survival figures as the base rate before you read any pitch. The most recent cohort with five years of follow-up is 2015, followed to 2020, and the series has not been updated since September 2022.
| Enterprises founded in 2015 | Survived 1 year | Survived 5 years |
|---|---|---|
| All new enterprises | 46.1% | 26.5% |
| Limited companies (aksjeselskap) | 66.7% | 43.8% |
Angel-investable startups are limited companies, so read the second line. It covers every new company, from consultancies to cafés, and is not specific to venture-backed startups.
The reasons companies fail tell you what to check before you invest. CB Insights’ post-mortem of 431 venture-backed shutdowns since 2023, the largest current sample, identified causes in 385 of them:
- Ran out of capital: 70 per cent
- Poor product-market fit: 43 per cent
- Bad timing or macro conditions: 29 per cent
- Unsustainable unit economics: 19 per cent
The shares add to more than 100 per cent because companies fail for more than one reason. CB Insights reads running out of capital as the final cause and not the root problem; the company ran out of money because something else was not working.
Before investing, investigate market need and unit economics, both of which are partly knowable in advance. Check how much runway the proposed round will provide.
Returns follow a power law
These studies describe British and American angel exits in the periods shown. Read the loss figures alongside the concentration of returns in a small number of successful exits.
| Study | Portfolio result | Exits returning less than capital | Where the returns came from |
|---|---|---|---|
| Wiltbank and Boeker, 2007 (US, 1,137 exits) | 2.6x over 3.5 years, about 27% IRR | 52% | 7% of exits returned more than 10x and produced 75% of all dollar returns |
| NESTA and BBAA, 2009 (UK, 406 exits) | 2.2x over 3.6 years, about 22% gross IRR | 56% | 9% of exits returned more than 10x and produced close to 80% of positive cash flows |
| Angel Resource Institute, 2016 (US) | 2.5x over 4.5 years, about 22% IRR | around 70% of investments | not reported separately |
A portfolio average does not describe the outcome of a typical position. In these samples, more than half of exits returned less than invested, while a small number generated much of the total return. A holding of one or two companies can perform very differently from the reported aggregate.
These results have different implications depending on your capital and experience.
- Before the first investment, decide how many positions you can fund over several years and size each ticket so the last one is still affordable. The portfolio needs enough positions to have a chance of including an unusually successful company.
- If you can follow on, keep capital in reserve for it. Fewer than a third of Norwegian angels can, and the ones who cannot hold a smaller share of their winners at exit.
- If you cannot reach portfolio size alone, invest alongside other angels. A group investing together gets to a diversified book on capital no single member has, and shares the screening work.
- If you have a sector background, spend your judgement where it is worth most. Use that experience to distinguish a strong investment from a convincing pitch.
The money is locked in for years
Plan for a long holding period. Five to seven years is a planning assumption, not a minimum every investment will meet, and some holdings last much longer.
The mean holding periods reported by the studies above (3.5 years, 3.6 years, 4.5 years) are averages of investments that actually exited. Failures exit fastest, so the positions that produce the returns take considerably longer than the mean. These figures describe the cited US and UK samples, not a Norwegian holding-period forecast.
In the meantime the money is not available: no secondary market to speak of, no dividend from a company reinvesting everything it earns, and no date on which anyone owes you anything. Invest only money you will not need in that period.
Why angels do it anyway
Angels invest for several reasons, none of which guarantees a return. Most members mention the work itself first.
- The return profile. Listed markets and property do not offer it. Angel returns are driven by company-specific outcomes and exit events, though downturns do compress valuations and close exit windows.
- The tail. A portfolio built over years, with enough positions to hold an outlier, has a real chance of one company paying for all the others.
- The work itself. Angels get to use experience that has nowhere else to go, sit close to companies being built, and work with people doing something difficult.