
Pre-money, post-money and what the percentage costs
The pre-money valuation (verdsettelse) is what the parties agree the company is worth before the new money arrives. Add the new capital and you have post-money, and your share is the new capital divided by post-money.
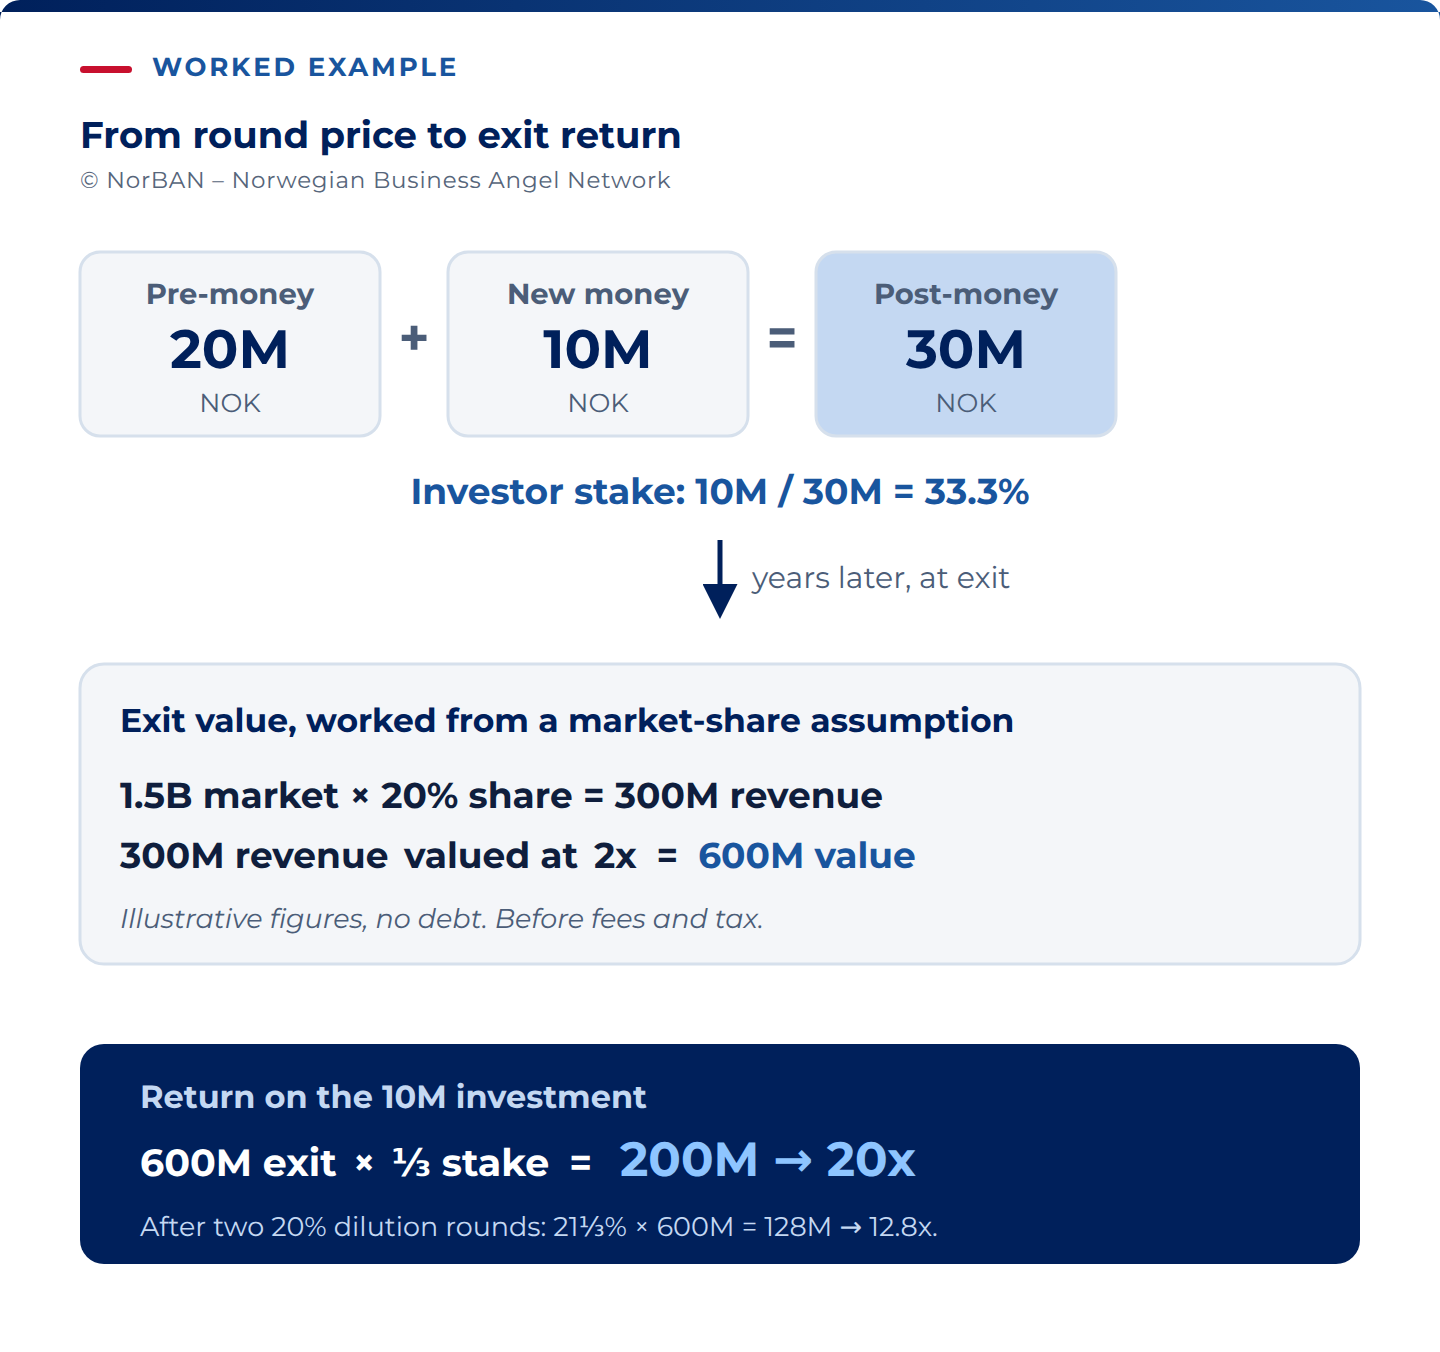
A round of NOK 10 million at NOK 20 million pre-money gives a post-money of NOK 30 million, and the incoming investors hold 10 of 30, or 33.3 per cent. The founders’ dilution (utvanning) is the mirror image: they held all of it and now hold two thirds.
The price per share, the subscription price (emisjonskurs, called tegningskurs in the statute), is pre-money divided by the agreed pricing share count. In this simple example, with no options or convertibles, that equals issued shares. The general meeting resolution must state it when the capital increase is resolved (aksjeloven § 10-1).
Ask for the share count and check the percentage yourself. A higher price gives you a smaller percentage, which later rounds will dilute further.
The method families, and where each one breaks
Use the five method families to understand how the founder reached the proposed price and how reliable its assumptions are. All five need a past, a forecast or a peer group, and a pre-revenue company has none in usable form.
| Family | Named methods | What it anchors on, and why it strains at pre-revenue |
|---|---|---|
| Cost | Replacement cost, book value | What has been spent, or what it would cost to rebuild the assets. Value sits in the option on the future rather than in the spend; a startup that is worth its costs is not worth investing in. |
| Income | Discounted cash flow, scenario-weighted and First Chicago variants, the venture capital method | Discounted future cash flows. The forecast is the thing in dispute, and small changes in growth or discount rate swing the answer by multiples. |
| Market | Revenue and earnings multiples, comparable transactions | Prices paid for comparable companies. There is no revenue to multiply, and Norwegian early-stage prices stay between the parties, so the comparison rests on what the people in the room have seen. |
| Factor | Berkus, Risk Factor Summation, Payne scorecard | Scored qualitative factors, benchmarked against a regional average pre-money — an American reference point, so the scores compare companies rather than fix a Norwegian price. |
| Stage | Stage bands | Where the company sits on a maturity path. Order of magnitude only; it gives the bracket, never the number. |
Factor methods are useful as assessment checklists. Apply one to two companies at the same stage to identify the differences between them.
- Berkus scores five elements (sound idea, management team, working prototype, quality board, product rollout) with a ceiling on each.
- Risk Factor Summation, from Ohio TechAngels, scores twelve risks from management and stage through funding, competition and technology.
- The Payne scorecard weights team, market size, product, competition and the need for further financing.
The stage ladder in practice
Most angel rounds are priced by stage and comparison. The ladder dates from 2018 and has not moved: an idea with a team and no product at roughly USD 250,000–500,000 pre-money, a company with revenue growth and a visible path to profitability at USD 5 million and above, and the intermediate stages spread between.
A 2018 dollar heuristic places a price in a bracket and no finer, and the brackets are American: read them as an order of magnitude for a Norwegian round, not as a price.
Round-size data provides a firmer point of comparison. EBAN’s Statistics Compendium reports what angels put in, which tells you whether the amount being raised is normal even where the price itself has no benchmark.
- The average European angel investment per company was EUR 204,900 in 2024, down from EUR 221,400 the year before.
- The average ticket per angel was EUR 25,600.
- Norway’s visible market, the part flowing through networks, was EUR 25.23 million across 90 rounds, roughly EUR 280,000 each.
Working backwards from the exit
Whatever valuation method you use, test the price against a plausible exit. Work backwards to see whether the potential return justifies the risk at today’s price. Build an exit case for the NOK 10 million investment and its initial one-third stake.
An addressable market of NOK 1.5 billion and a 20% share give NOK 300 million of revenue. At twice sales, enterprise value is NOK 600 million. Assume zero net debt so equity value is also NOK 600 million.
Assume two later rounds each dilute the existing holders by exactly 20%. They retain 80% × 80% = 64% of their original stake, so the initial one-third becomes 21⅓%. At a NOK 600 million equity exit, that holding returns NOK 128 million on NOK 10 million invested, or 12.8 times the investment.
This simple example assumes proportionate equity proceeds, with no further pool increases, converting instruments, debt adjustments, preferences, fees or taxes. Model those separately where they apply.
At NOK 40 million pre-money, the NOK 10 million investment buys 20% initially and 12.8% after the same later dilution. A NOK 600 million equity exit then returns NOK 76.8 million, or 7.68 times the investment: 40% less than the first case. It takes a NOK 1 billion exit to produce the earlier NOK 128 million return.
Market size, market share and the exit multiple remain uncertain. Test how the return changes when each assumption is less favourable.
Test the proposed price on one page. Keep the assumptions so you can compare later cases.
- Take the share count and the round size and work out your percentage after the round.
- Write down the exit the business has to reach: the market, a plausible share of it, and a sales multiple you would defend to another investor.
- Apply each later round’s dilution, including pools and converting instruments, then calculate the remaining return multiple.
- Run it again with each of the three at its cautious end. If the return survives only the optimistic case, the price is too high for the risk.
With a sector background, spend the time on market share and multiple, where your judgment is worth most. In a syndicate, have one person run the chain and circulate it before the price is discussed, so the group argues about the same numbers.
What actually moves the number
Before responding to the founder’s proposed price, weigh the factors that influence it more than the model:
- Competition for the deal. A round with three interested investors prices differently from a round with one, so find out early who else is looking. It is the largest single factor and the least discussed.
- The team. Whether these people can carry the company to the point where the next investor takes over.
- The quality of traction. Paying customers outrank pilots, pilots outrank letters of intent, and a signed enterprise agreement with no revenue attached is a sales document.
- Capital efficiency. How far the company got on what it has spent tells you what it will do with what you give it.
- What the next round has to look like. The constraint most angels underweight, and the one that decides whether your position is ever worth anything.
A price the next financing cannot clear forces a down round, and down rounds destroy value beyond the arithmetic. They trigger price protection, reset the founders’ incentives and signal distress.
Some examples: Klarna’s valuation fell from USD 45.6 billion in June 2021 to USD 6.7 billion in its July 2022 raise, a fall of 85 per cent. Oda raised USD 151 million in December 2022 at about USD 353 million, down from roughly USD 900 million in April 2021, or 61 per cent.
Neither company was failing at the moment of the reset; both had been priced for a future that did not arrive on schedule.
When the price cannot be agreed
If you cannot agree a price, consider whether to defer that decision. A convertible loan (konvertibelt lån) lends the money now and converts it into shares at the next priced round, usually at a discount and under a valuation cap.
Norwegian law provides for it directly. A company can take up loans carrying a right to demand shares issued, and the general meeting resolves it (aksjeloven § 11-1).
Deferring the price means giving up control over it. A later negotiation, which you may not participate in, sets the price within the boundaries of the cap and discount.
The cap is a ceiling on the conversion valuation. Negotiate it carefully, then compare the cap price with the discount price under the instrument’s definitions. A high cap or an uncapped discount can leave early money converting at a price you consider too high.